
A banking system refers to the network of banks and other regulated financial institutions that provide banking services within a country. These services include accepting deposits, granting loans, facilitating payments and supporting financial transactions.
A country banking system plays an important role in its economic development. It helps individuals and businesses save money, access credit, make payments and carry out financial transactions. Banks also help channel funds from people who have savings to businesses and individuals who need financing.
Because of their importance to the economy, banks operate under regulations established by the relevant financial authorities.
Banking System in India
India has a large and diverse banking system, with the Reserve Bank of India (RBI) serving as its central bank and principal banking regulator.
The RBI is responsible for important functions such as formulating monetary policy, issuing currency, regulating banks, managing foreign exchange reserves and overseeing the country’s payment systems.
The Indian banking system serves customers in both rural and urban areas. While some financial institutions concentrate on particular communities and sectors, others provide services to individuals, businesses and government institutions across the country.
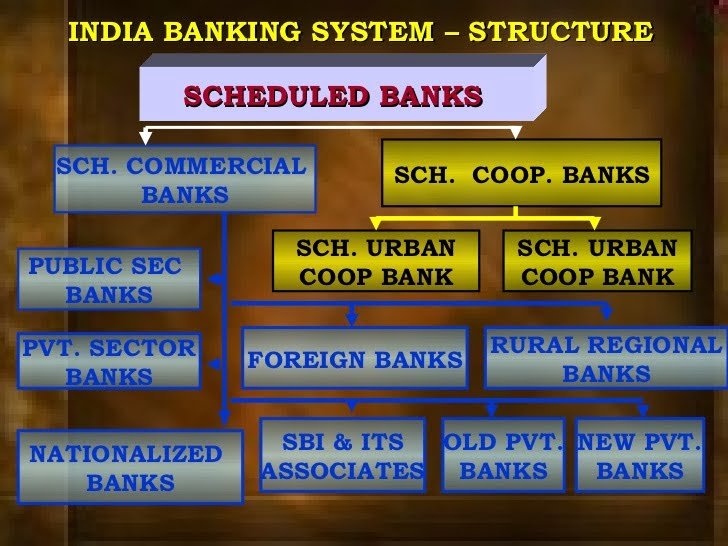
The banking structure includes commercial banks, cooperative banks and specialised banking institutions. These institutions help mobilise savings, provide credit and support economic activities in different parts of India.
Classification of Banks in India
The banking system in India includes different categories of banks. Each category has its own purpose, regulatory requirements and areas of operation.
1. Commercial Banks
Commercial banks accept deposits from customers and provide loans and other banking services. Their customers include individuals, businesses, corporate organisations and government institutions.
They operate under the Banking Regulation Act, 1949, and are regulated by the Reserve Bank of India.
Commercial banks in India include the following categories:
Public Sector Banks
These are banks in which the government has majority ownership. They provide services such as savings accounts, current accounts, loans, payment facilities and other financial products.
The State Bank of India and other government-owned banks fall into this category.
Private Sector Banks
Private sector banks are banking companies in which private shareholders hold the controlling ownership. They provide banking services to individuals, businesses and other customers.
Foreign Banks
These are banks headquartered outside India that operate in the country through authorised branches or other permitted arrangements. They must comply with applicable Indian banking regulations.
Regional Rural Banks (RRBs)
Regional Rural Banks were established to improve access to banking and credit facilities in rural communities.
They provide financial services to farmers, agricultural workers, small businesses and other customers in their designated areas. They are jointly owned by the Central Government, the relevant State Government and a sponsor bank.
2. Cooperative Banks
Cooperative banks are financial institutions established on cooperative principles. They are owned by their members and generally operate to meet the financial needs of their communities.
They provide services such as savings accounts, deposits and loans. Their activities support individuals, small businesses, farmers and other groups that may have limited access to conventional banking services.
Cooperative banks in India are broadly classified into two groups:
- Urban Cooperative Banks: These mainly serve customers in towns and cities, including small businesses, traders and individuals.
- Rural Cooperative Credit Institutions: These serve rural communities and provide credit for agricultural and other rural economic activities.
Cooperative banks are subject to applicable cooperative laws as well as banking regulations. The Reserve Bank of India and other relevant authorities, including NABARD in the rural cooperative banking sector, have regulatory and supervisory responsibilities.
3. Payments Banks
Payments banks are a specialised category of banks introduced by the Reserve Bank of India to improve access to basic banking and payment services.
They are designed to serve customers who may have limited access to conventional banking facilities, including people in rural and underserved communities.
Payments banks can provide services such as:
- Savings and current deposit accounts, subject to applicable limits.
- ATM and debit cards.
- Mobile banking.
- Internet banking.
- Domestic money transfers and payment services.
However, payments banks operate under restrictions that distinguish them from ordinary commercial banks. They cannot undertake lending activities in the same way as conventional banks.
4. Small Finance Banks
Small Finance Banks (SFBs) were introduced to improve financial inclusion by providing banking services to people and businesses that may not be adequately served by traditional banks.
Their major customers include:
- Small and marginal farmers.
- Micro and small businesses.
- Small industries.
- Low-income households.
- Individuals and organisations in underserved communities.
Small Finance Banks can accept deposits and provide loans, subject to the rules and licensing conditions established by the Reserve Bank of India.
Their activities help improve access to formal banking services, especially among people who may find it difficult to obtain credit from larger financial institutions.
5. Local Area Banks
Local Area Banks are small private-sector banks established to provide banking services within limited geographical areas.
Their purpose is to mobilise savings in their areas of operation and make financial resources available to local communities and businesses.
They are different from large commercial banks because their operations are geographically restricted.
The Role of the Reserve Bank of India in the Banking System
The Reserve Bank of India is the central bank of the country. It plays a major role in maintaining the stability and proper functioning of India’s financial system.
Some of its important responsibilities include:
- Monetary policy: The RBI formulates and implements monetary policy to maintain price stability while supporting economic growth.
- Currency issuance: It manages the issue of banknotes in India, subject to the applicable legal framework.
- Bank regulation: It regulates and supervises banks to promote financial stability and protect the interests of customers.
- Foreign exchange management: It manages India’s foreign exchange reserves and administers relevant foreign exchange regulations.
- Payment systems: It oversees and regulates payment and settlement systems to support secure financial transactions.
- Banker to the government: It performs banking functions for the Central Government and State Governments.
Historical Development of the Banking System in India
The Indian banking system has undergone several important changes since the establishment of the Reserve Bank of India.
Some major historical developments include:
- 1935: The Reserve Bank of India commenced operations on April 1, 1935.
- 1949: The RBI was nationalised on January 1, 1949. The Banking Regulation Act also came into force in March 1949, providing an important legal framework for banking regulation.
- 1955: The Imperial Bank of India was taken over and became the State Bank of India.
- 1969: The Indian government nationalised 14 major commercial banks to expand banking services and improve access to credit.
- 1980: Six additional commercial banks were nationalised.
- 1990s: Economic and financial reforms encouraged greater competition and the entry of new private-sector banks.
- 2000s onwards: Banking services expanded through technology, digital payments, mobile banking and other financial innovations.
These developments helped transform India’s banking sector from a system dominated by a limited number of institutions into a more diverse industry serving different categories of customers.
Conclusion
The banking system in India is an important part of the country economy. Through the activities of commercial banks, cooperative banks, payments banks, small finance banks and other financial institutions, people and businesses can access services that support saving, borrowing and financial transactions.
The Reserve Bank of India plays a central role in regulating the sector and maintaining financial stability. As banking services continue to develop, technology and financial inclusion remain important parts of the industry’s growth.
Understanding the different categories of banks helps explain how the Indian banking system serves both urban and rural communities.
